Contact us
Send Us Your Case Details
We’ll respond and let you know the best way to proceed with your case.

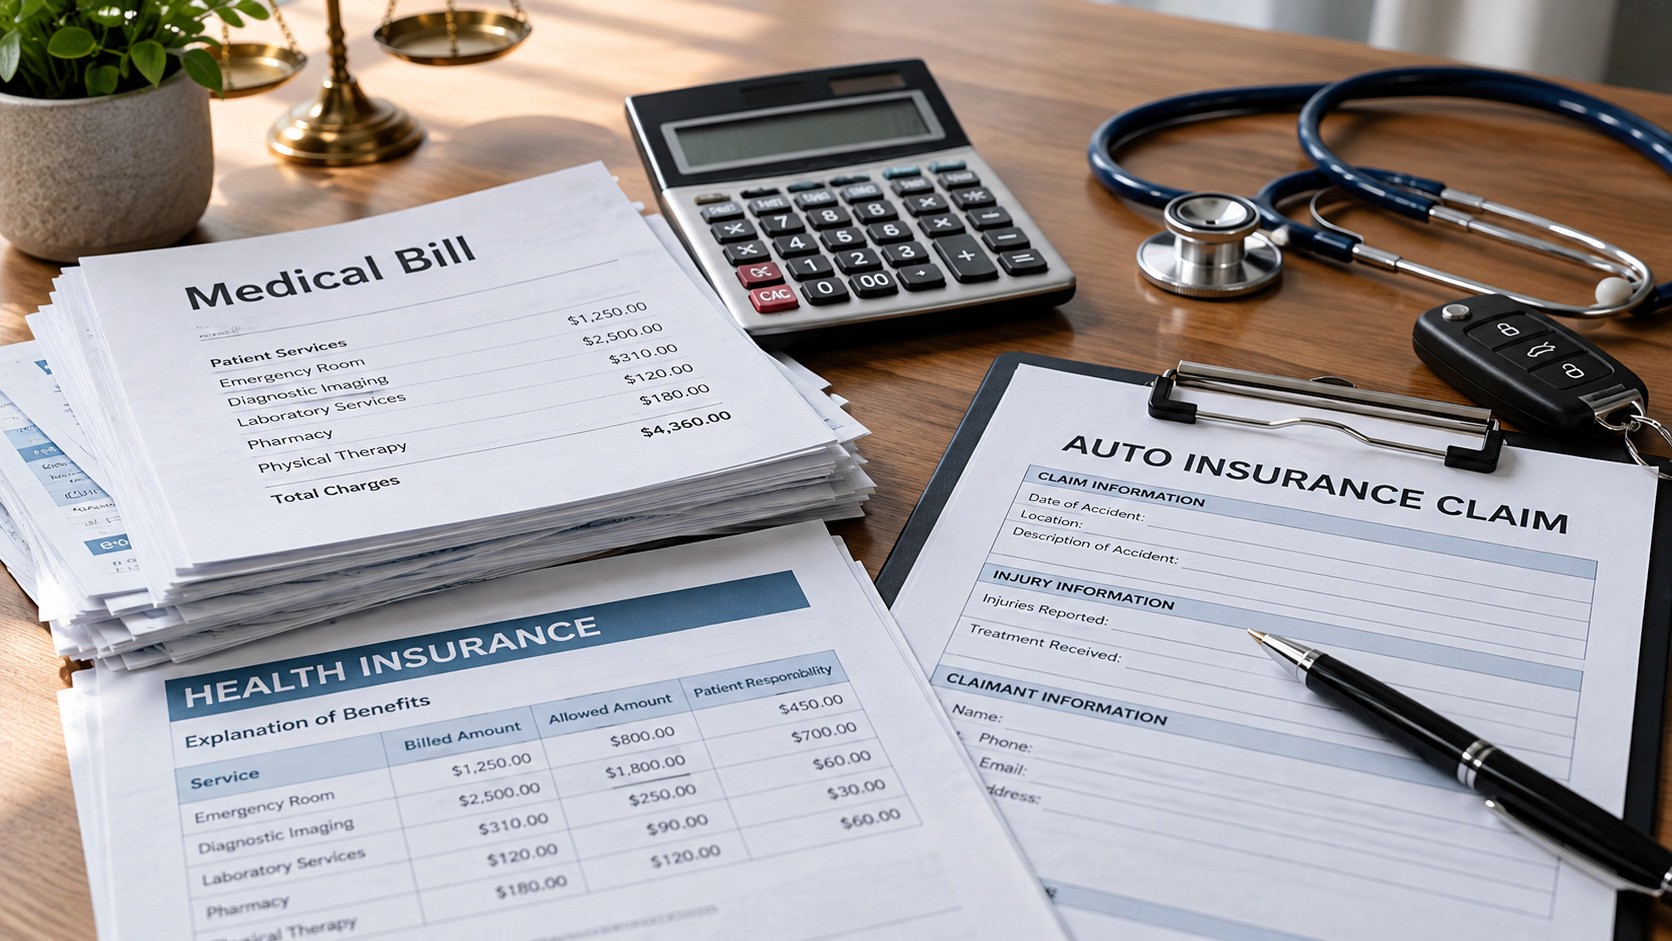
The bills usually arrive before the answers do. A few days after a crash, you may have an ambulance invoice, an emergency room statement, and a stack of follow-up appointments on the calendar. Meanwhile, the insurance claim against the driver who hit you has barely started. It is one of the most stressful parts of being hurt in a Georgia car accident, and one of the most common questions our team hears.
Here is the short answer. In Georgia, the at-fault driver’s insurance company generally does not pay your medical bills as you receive treatment. It usually pays once, at the end, when your claim settles or a court enters a judgment. Until then, your bills are typically handled through a combination of your own coverage, such as Medical Payments coverage, health insurance, Medicare or Medicaid, or workers’ compensation if you were on the job, and in some cases through arrangements with providers who agree to wait for the outcome of your case.
Each of those sources comes with its own rules, and several of them expect to be repaid from your settlement. This guide walks through how each one works under Georgia law, what changed with the state’s 2025 tort reform law, and the practical steps that protect both your health and your claim while you wait.
Georgia is an at-fault state, sometimes called a tort state. The driver who caused the crash, and that driver’s liability insurer, are responsible for the injuries they caused. Georgia does not require drivers to carry Personal Injury Protection (PIP), the no-fault coverage that pays medical bills up front in states like Florida.
That sounds like good news for an injured person, and in many ways it is. But it also explains the waiting period. A liability insurer has no obligation to pay your doctor while you are still treating. Before it pays anything, the insurer will usually want to:
Fault questions matter in Georgia because of the state’s modified comparative negligence rule in O.C.G.A. § 51-12-33. If you are found partly at fault, your recovery is reduced by your percentage of fault. If you are found 50 percent or more at fault, you cannot recover damages from the other driver at all. Insurers know this, and they often look for ways to shift blame before they discuss payment.
Because the liability claim usually resolves in one lump sum near the end, something else has to carry your medical bills in the meantime. That is where the following sources come in.
Most people use more than one of these sources at the same time. Knowing what you have, and the order in which to use it, can make a real difference in how much you keep at the end.
MedPay is optional coverage that many Georgia drivers have without realizing it. It pays reasonable and necessary medical expenses after a crash regardless of who caused it, so you do not have to wait for a fault decision. Depending on the policy, it may also cover passengers in your vehicle and members of your household.
Because MedPay is first-party coverage, you file the claim with your own insurer. Using it does not mean you are admitting fault, and it does not take away your right to pursue the at-fault driver. Pull out your declarations page or call your agent to see whether you carry it and what the limit is. MedPay limits are often modest, so it tends to cover early bills like the ambulance and emergency room rather than an entire course of treatment.
For most people, health insurance is the backbone of medical coverage during a pending claim. You can and generally should use it, even though another driver caused the crash. Give your health insurance information to every provider you see and ask them to bill it.
Using health insurance has real advantages. In-network providers have agreed to contracted rates, your care is less likely to be delayed by billing disputes, and your accounts are less likely to be sent to collections while the case moves forward. You will still be responsible for your usual deductibles and copays, and those out-of-pocket amounts are part of what you can seek from the at-fault driver.
The catch is that your health plan may ask to be repaid from your settlement. How much it can recover depends on the type of plan, which we cover in the next section.
If you are covered by Medicare or Georgia Medicaid, those programs will generally pay for accident-related care. Both have strong repayment rights. Medicare’s right to recover its conditional payments comes from federal law. Georgia Medicaid, administered by the Department of Community Health, has a lien under O.C.G.A. § 49-4-149 on money a recipient recovers from a liable third party for care Medicaid paid for. These claims must be identified and resolved before settlement funds are distributed.
If the crash happened while you were driving for your job, such as making deliveries, traveling between job sites, or running work errands, Georgia workers’ compensation may pay your authorized medical treatment and a portion of your lost wages. Workers’ compensation is a no-fault system, so benefits do not depend on proving the other driver was careless. You can often pursue the workers’ compensation claim and a separate claim against the at-fault driver at the same time. The employer or its insurer may have a lien on the third-party recovery, and coordinating the two claims takes careful planning.
UM coverage protects you when the at-fault driver has no insurance or not enough insurance to cover your losses. Under O.C.G.A. § 33-7-11, UM coverage is included in a Georgia auto policy unless the policyholder rejected it in writing, and for policies issued or renewed since 2009, the default is “added on” coverage that stacks on top of the at-fault driver’s liability limits rather than being reduced by them.
UM coverage usually works like the liability claim. It typically pays when the claim is resolved, not bill by bill. But knowing it exists early matters, because it can change how your case is valued and how long you can afford to wait for a fair result.
Some injured people have no health insurance, or have plans with deductibles so high that care is out of reach. In those situations, some providers will treat a patient and wait to be paid from the settlement or verdict. This is often documented in a letter of protection. These arrangements can make necessary care possible, but they carry new risks under Georgia’s 2025 tort reform law, discussed below, and should be considered with your attorney’s guidance.
Many injured people are surprised to learn that the money paying their bills today may have a claim on their settlement tomorrow. Georgia law gives some of these payers strong rights and limits others. Understanding the difference is one of the most valuable things an attorney does at the end of a case.
Under O.C.G.A. § 44-14-470, hospitals, nursing homes, physician practices, and providers of traumatic burn care can claim a lien for their reasonable charges against your cause of action against the at-fault party. A few points about these liens are important:
Georgia is more protective of injured people than many states when it comes to health insurance reimbursement. Under O.C.G.A. § 33-24-56.1, a health or medical benefit provider covered by the statute can seek reimbursement from your recovery only if you have been fully and completely compensated for all of your economic and noneconomic losses. Even then, the reimbursement claim is reduced by its pro rata share of the attorney’s fees and litigation expenses that produced the recovery. The statute also bars the benefit provider from withholding or offsetting your benefits to pressure you into repaying it.
There is a major exception. Self-funded employer health plans governed by the federal ERISA law, along with certain other federal plans and programs, generally are not bound by Georgia’s statute. Those plans may have stronger repayment rights based on their plan language. Determining which kind of plan you have, and requesting the actual plan documents, is an essential step.
If workers’ compensation paid benefits, the employer or its insurer may assert a lien against your recovery from the at-fault driver under O.C.G.A. § 34-9-11.1. That lien is limited to benefits actually paid and is recoverable only if you have been fully and completely compensated, taking into account all of your losses.
| Source | When it typically pays | Repayment from your settlement |
|---|---|---|
| MedPay | As bills come in, regardless of fault | Depends on your policy and Georgia’s full compensation rules |
| Health insurance (fully insured plan) | As you treat | Only if you are fully compensated, reduced by a share of fees (O.C.G.A. § 33-24-56.1) |
| Self-funded ERISA plan | As you treat | Often required by plan terms under federal law |
| Medicare | As you treat | Yes, conditional payments are recovered under federal law |
| Georgia Medicaid | As you treat | Yes, lien under O.C.G.A. § 49-4-149 |
| Workers’ compensation | As you treat | Lien only if you are fully and completely compensated (O.C.G.A. § 34-9-11.1) |
| Providers who wait or file liens | At settlement or judgment | Paid from the recovery |
| At-fault driver’s liability insurer | At settlement or judgment | Not applicable |
| Your UM coverage | When the claim is resolved | Not applicable |
In April 2025, Governor Brian Kemp signed Senate Bill 68, a broad tort reform law. One of its most important changes for car accident victims is a new statute, O.C.G.A. § 51-12-1.1, which governs how medical expenses are proven. It applies to claims arising from accidents that happened on or after April 21, 2025.
Under the new law, damages for medical expenses are limited to the reasonable value of medically necessary care. When a jury decides what that reasonable value is, it may now consider both the amounts your providers charged and the amounts actually needed to satisfy those charges under a health insurance contract or workers’ compensation, regardless of whether insurance was actually used. In practical terms, the defense can now point to the lower negotiated rates that insurers pay and argue that your medical damages should be measured by those figures.
SB 68 also put letters of protection under a spotlight. When treatment is provided under a letter of protection or a similar arrangement, the following are now relevant and discoverable in a lawsuit:
None of this means a person without insurance should go without care. It does mean that how your treatment is paid for can now affect how your medical damages are presented and challenged. Using your health insurance when you have it, keeping complete billing records, and making treatment decisions based on medical need rather than on the claim are more important than ever. If your accident happened before April 21, 2025, different rules may apply to the medical damages portion of your case, which is another reason the accident date is one of the first things a lawyer will confirm.
You cannot control how fast the insurance company moves, but you can control a lot of what happens while you wait. These steps help on both fronts.
If your crash happened in Gwinnett County, our guide on how to get your car accident report in Gwinnett County walks through obtaining one of the first documents insurers and attorneys will ask for.
The medical bill question is rarely just about the bills. It touches insurance coverage, lien law, federal benefit rules, and now the evidence rules created by SB 68. Handling it well can change what you actually take home at the end of your case.
When you work with Eric Sterling Law Firm, our team can:
Our firm is based in Lawrenceville and represents car accident victims across Georgia. We believe in our clients, and we stop at nothing to protect their rights while they focus on healing.
If you were hurt in a crash and the bills are piling up, call us at 844-48-ES LAW or send us your case details. We will listen to what happened, review your coverage, and explain your options under Georgia law.
Eric Sterling Law Firm, 190 S Clayton St. Suite 7, Lawrenceville, GA 30046
This article provides general information about Georgia law and is not legal advice for any individual situation. Reading it does not create an attorney-client relationship. Every case depends on its own facts and insurance policies.